
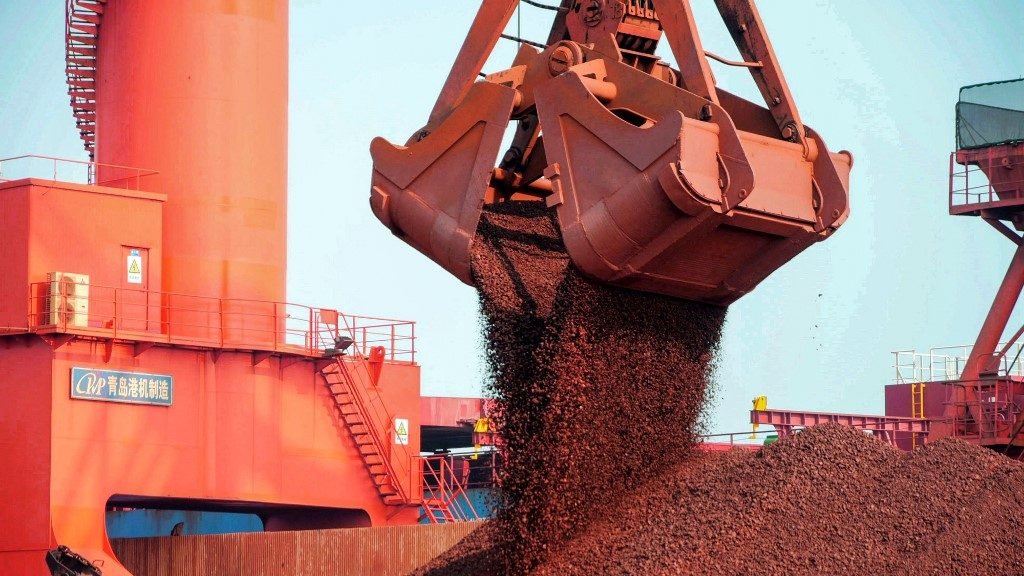
Iron ore futures have climbed above CNY 680 per tonne, recovering from four-year lows as stronger Chinese steel production and better-than-expected economic growth provide fresh support for demand expectations. China’s daily crude steel output increased by 1.9% month over month to 2.45 million tonnes in September, marking the first monthly increase since June and offering a positive signal for iron ore consumption.
China’s economy also expanded by 4.5% year over year in the third quarter, accelerating from 4.3% in the previous quarter and exceeding forecasts of 4.4%. However, the recovery in iron ore prices faces significant headwinds. Ample global supplies, expanding mining capacity and expectations of higher shipments in the fourth quarter could limit further gains, while a weaker outlook for global steel demand adds uncertainty to the longer-term picture.
Market Snapshot
| Market indicator | Latest development |
|---|---|
| Iron ore price | Above CNY 680 per tonne |
| Recent price trend | Recovery from four-year lows |
| China’s September daily crude steel output | 2.45 million tonnes |
| Monthly change in steel output | +1.9% |
| China’s Q3 GDP growth | +4.5% year over year |
| Previous quarter’s GDP growth | +4.3% |
| Q3 growth forecast | +4.4% |
| Global steel demand outlook | World Steel Association forecasts a 0.1% contraction in 2026 |
| Main market tension | Improving Chinese production versus ample global supply |
Current Iron Ore Price Action
Iron ore has rebounded above CNY 680 per tonne after reaching four-year lows, with stronger steel production and better Chinese economic growth helping improve sentiment.
The recovery suggests that the market is responding to signs of improved industrial activity rather than relying solely on expectations of future stimulus. The increase in Chinese steel output is particularly relevant because steelmakers are the principal source of demand for iron ore.
Nevertheless, the rebound remains vulnerable. A price recovery from an extended low does not necessarily indicate that the market has entered a sustained uptrend, especially when global supply is abundant and expectations for future steel demand remain subdued.
Traders will be watching whether higher steel production continues into the coming months and whether it translates into stronger iron ore purchasing.
China Steel Production: First Monthly Increase Since June
China’s daily crude steel output rose 1.9% month over month to 2.45 million tonnes in September, marking the first monthly increase since June.
The improvement was supported by robust steel exports and expectations of stronger seasonal domestic demand. Higher steel production generally increases the need for iron ore, providing a potential source of support for prices.
However, the sustainability of the increase remains important. If steelmakers maintain higher production rates, iron ore demand could improve. If output subsequently weakens because of poor margins, production restrictions or disappointing end-user demand, the latest increase may provide only temporary support.
The market will therefore be looking for evidence that September’s rebound represents a continuing improvement rather than a short-lived recovery.
China’s Economic Growth Strengthens the Demand Outlook
China’s economy grew by 4.5% year over year in the third quarter, accelerating from 4.3% in the previous quarter and exceeding the forecast of 4.4%.
Stronger-than-expected economic growth can support industrial activity and improve expectations for construction, manufacturing and infrastructure-related steel consumption. The data therefore provide a more constructive backdrop for iron ore than a weaker growth outcome would have done.
However, economic growth does not automatically translate into stronger steel demand. The composition of growth, construction activity, manufacturing orders and steel export performance will determine how much additional demand reaches the iron ore market.
For traders, the next challenge is determining whether stronger headline growth can generate sustained demand for steel and raw materials.
Global Iron Ore Supply: A Major Constraint on Prices
Despite improving Chinese production, global iron ore supply remains a significant headwind. Expanding mining capacity and expectations of higher shipments in the fourth quarter could increase the volume of material available to steelmakers.
When supply grows faster than consumption, producers and exporters may face greater competition to sell their output. This can limit price recoveries even when demand improves in one major market.
The timing of additional shipments will be particularly important. If supply increases while Chinese steel demand remains firm, the market may absorb the additional volumes more easily. If demand weakens at the same time, the resulting surplus could place renewed pressure on prices.
The balance between new supply and actual steel consumption is therefore likely to determine whether the current rebound can be sustained.
Bullish Sentiment: Factors Supporting Iron Ore Prices
- Chinese steel production rebounds: September’s 1.9% monthly increase in daily crude steel output provides evidence of improving near-term industrial demand.
- Economic growth exceeds expectations: China’s third-quarter growth of 4.5% surpassed the 4.4% forecast and accelerated from the previous quarter.
- Seasonal demand potential: Expectations of stronger domestic demand could encourage steelmakers to maintain or increase production.
- Robust steel exports: Export demand has helped support Chinese steel output, potentially sustaining demand for iron ore.
- Recovery from four-year lows: The move above CNY 680 indicates that buying interest has returned as market conditions improve.
Bearish Sentiment: Factors Limiting the Recovery
- Ample global supply: Abundant availability can limit the price impact of stronger Chinese demand.
- Higher fourth-quarter shipments: Expected increases in shipments could add further material to an already well-supplied market.
- Expanding mining capacity: Additional production capacity could keep supply elevated and increase competition among exporters.
- Weak global steel demand outlook: The World Steel Association’s forecast of a 0.1% contraction in global steel demand in 2026 points to a challenging demand environment.
- Uncertain durability of Chinese production growth: If the September increase proves temporary, the market may struggle to maintain its recovery.
Iron Ore Price Forecast: What Traders Are Watching
Iron ore’s recovery above CNY 680 per tonne has improved the immediate outlook, but the market still faces a conflict between stronger Chinese production and expectations of abundant global supply.
Traders will be monitoring three key developments:
- Chinese steel production: Whether output continues to increase beyond September and generates sustained demand for raw materials.
- Fourth-quarter shipments: Whether additional export volumes deepen the supply balance or are absorbed by stronger steelmaking activity.
- Global steel demand: Whether construction, manufacturing and steel consumption improve enough to offset the World Steel Association’s weaker demand outlook.
The supplied information does not establish a reliable numerical price target or specific technical support and resistance levels. Further price-history data and updated supply-demand figures would be needed to identify those levels with confidence.
Iron Ore Supply Outlook
The supply outlook remains a central risk for the iron ore market. Expanding mining capacity and higher expected shipments could limit the impact of improving Chinese demand, particularly if other major steel-producing regions experience weak consumption.
If additional supply arrives while Chinese steel production continues to strengthen, the market may remain relatively balanced. However, if shipments rise faster than consumption, inventories could build and prices could come under renewed pressure.
The most important indicator will be whether demand growth can absorb additional export volumes. A recovery driven by higher production is more sustainable when it is accompanied by improving consumption and manageable inventory levels.
Demand Outlook: China Remains the Key Driver
China’s steel sector remains central to the near-term iron ore outlook. The recent increase in crude steel production and stronger-than-expected GDP growth provide reasons for cautious optimism.
However, the longer-term picture is less certain. The World Steel Association’s forecast of a 0.1% contraction in global steel demand in 2026 suggests that the recovery in Chinese output is taking place against a challenging international backdrop.
Steel exports may help support Chinese production, but sustained demand will also depend on domestic construction, manufacturing activity and the profitability of steelmakers. If end-user demand improves, iron ore could receive more durable support. If demand remains weak, increased production could instead add to pressure on steel prices and raw material purchasing.
Market Outlook for the Coming Sessions
Iron ore is showing signs of recovery as stronger Chinese steel output and better-than-expected economic growth improve sentiment. The rise above CNY 680 per tonne marks a rebound from four-year lows, but the market has not yet overcome its underlying supply challenges.
The outlook depends on whether higher steel production can continue and absorb the additional volumes expected from global exporters. Persistent demand strength could support further price stabilisation, while rising shipments and weak global steel consumption could reverse the recovery.
For now, iron ore has a cautiously constructive near-term outlook but remains exposed to significant supply-side pressure. Traders should look for confirmation that China’s production rebound is sustainable and monitor fourth-quarter shipment trends before assuming that the market has entered a lasting upward trend.
Today Markets Analysis
Today Markets views iron ore as a market attempting to recover on improving Chinese economic and steel-production data while facing a substantial supply overhang.
The latest figures provide a positive near-term signal, particularly because steel output increased for the first time since June. However, rising mining capacity and higher expected shipments could prevent demand improvements from translating into sustained price gains.
The key question is whether Chinese steel production can strengthen enough to absorb additional global supply. Until that balance becomes clearer, price recoveries may remain vulnerable to changes in production, shipments and steel-demand expectations.
Currency Hedger View
For steel manufacturers, construction businesses, mining companies and commodity importers, iron ore price movements can affect raw-material costs, purchasing budgets and profit margins. Companies trading internationally may also face exchange-rate risk when payments and revenues are denominated in different currencies.
Businesses with recurring cross-border commodity payments may benefit from reviewing their foreign-exchange exposure alongside their raw-material purchasing strategy. Appropriate currency hedging arrangements can help improve budget certainty, although they do not eliminate commodity-price risk or guarantee a particular financial outcome.
Manage your currency exposure with Currency Hedger:
Disclaimer: This article is for informational and educational purposes only and does not constitute investment, trading, financial or hedging advice. Commodity prices are volatile, and market forecasts are not guarantees of future performance. Trading futures and other leveraged instruments involves significant risk, including the potential loss of capital. Businesses should assess their individual circumstances and seek independent professional advice where appropriate.

Leave A Comment