
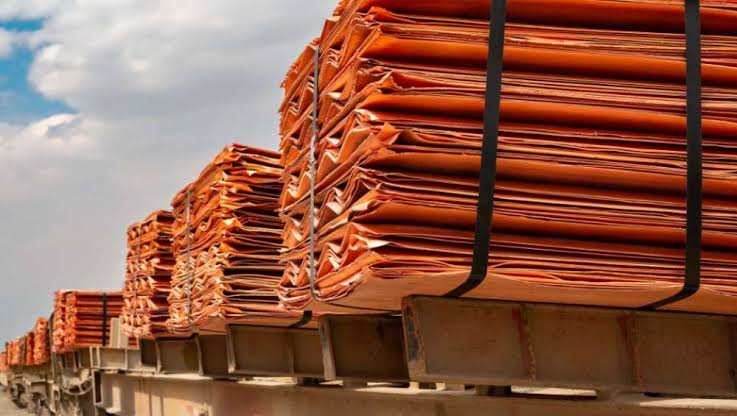
Copper prices are rebounding towards $6.30 per pound on Wednesday, recovering from four-month lows as tightening physical supply in China provides renewed support to the market. The recovery reflects growing concerns over the availability of refined copper in the world’s largest consuming market, where record import premiums, reduced shipments and lower domestic smelter production are tightening supply conditions.
Investor interest in artificial intelligence infrastructure has also returned, adding another layer of support. Strong earnings from neocloud provider CoreWeave have helped revive enthusiasm around data centre investment, a sector that requires substantial quantities of copper for electrical systems, power networks and infrastructure.
However, the outlook remains mixed. Political uncertainty in the United States and the potential for tighter AI regulation could weigh on expectations for future data centre expansion, while the recent recovery still needs to overcome the broader pressure that pushed prices to four-month lows.
Market Snapshot
| Market Indicator | Latest Development |
|---|---|
| Copper futures | Climbed towards $6.30 per pound |
| Recent price trend | Rebounded from four-month lows |
| China physical market | Tightening supply conditions |
| Chinese import premiums | Reached record levels in recent weeks |
| Refined copper shipments | Declined this year |
| Chinese smelter production | Reduced amid higher ore costs and weaker margins |
| AI infrastructure demand | Renewed investor interest |
| Key risk | US political and regulatory uncertainty |
Copper Price Action: Recovery Follows Four-Month Lows
Copper futures have recovered towards $6.30 per pound, reversing some of their recent weakness as the physical market in China shows signs of tightening.
The rebound follows a decline that brought prices to four-month lows. However, the latest move suggests that underlying supply concerns remain an important source of support, particularly as Chinese buyers face difficulties securing sufficient refined copper.
The recovery is being reinforced by renewed interest in industrial metals linked to the artificial intelligence investment cycle. Copper remains essential to electricity distribution, data centre construction, cooling systems and the wider power infrastructure required to support expanding computing capacity.
China Copper Supply Tightens as Import Premiums Surge
China remains the central influence on the global copper market, and current developments in its physical supply chain are providing a significant source of price support.
Import premiums have reached record levels in recent weeks, reflecting stronger competition for available material. At the same time, refined copper shipments into the country have declined this year, making it more difficult for buyers to replenish domestic inventories.
The situation has been complicated by substantial volumes of copper being redirected towards the United States ahead of potential import tariffs. This diversion has reduced the amount of material available to other markets and added pressure to China’s efforts to secure sufficient supplies.
The combination of lower shipments, high premiums and inventory replenishment difficulties has strengthened concerns over near-term physical availability.
Chinese Smelter Production Faces Margin Pressure
Domestic Chinese smelters have also reduced production as rising ore costs and weaker profit margins put pressure on operations.
Higher raw material costs can squeeze processing margins, particularly when smelters struggle to secure sufficient copper concentrate on favourable commercial terms.
Reduced production limits the availability of refined copper within China and could increase the country’s reliance on imports at a time when international supply flows are already being disrupted.
The market will therefore be watching for further evidence of production adjustments and whether import availability improves in the coming weeks.
AI Infrastructure Revives Copper Demand Expectations
Renewed investor interest in artificial intelligence has provided another supportive influence for copper prices.
Strong earnings from neocloud provider CoreWeave have helped restore confidence in the AI infrastructure investment theme. The expansion of data centres requires extensive electrical infrastructure, including power distribution equipment, cabling, transformers and grid connections.
Copper is a critical material across these applications, making it an important beneficiary of sustained investment in data centre capacity and electricity networks.
However, the relationship between AI investment and copper demand is not immediate. Actual consumption will depend on the pace of construction, infrastructure spending and the ability of electricity networks to accommodate new facilities.
US Political Uncertainty Creates a Demand Risk
Despite the renewed enthusiasm surrounding AI infrastructure, political developments in the United States introduce an additional source of uncertainty.
A Democratic sweep in the US midterm elections could increase the prospect of tighter AI regulation and potentially slow the development of data centres.
Any regulatory changes that delay infrastructure projects or reduce investment appetite could weaken expectations for future copper consumption.
For the market, the central question is whether physical supply constraints in China and continued global electrification investment will outweigh potential policy-related pressure on US data centre development.
Bullish Sentiment
- Tightening Chinese supply: Reduced refined copper shipments and difficulties replenishing inventories are supporting physical market concerns.
- Record import premiums: Higher premiums indicate increased competition for available copper in China.
- Lower smelter production: Rising ore costs and weaker margins have encouraged Chinese smelters to reduce output.
- Copper redirected to the US: Potential import tariffs have contributed to changes in global trade flows, reducing material available to other markets.
- AI infrastructure investment: Renewed enthusiasm around data centre expansion is strengthening long-term demand expectations for copper.
Bearish Sentiment
- Recovery remains incomplete: Copper is rebounding from four-month lows, and the durability of the recovery remains uncertain.
- US regulatory risk: Potentially tighter AI regulation could slow data centre investment and reduce future demand expectations.
- Investment uncertainty: Changes in US policy could affect the timing and scale of infrastructure spending.
- Dependence on Chinese demand: The market remains highly sensitive to China’s ability to sustain industrial consumption and replenish inventories.
Copper Price Forecast: What Traders Are Watching
The immediate outlook for copper will depend heavily on developments in China’s physical market.
Import premiums, refined copper shipments, smelter production and inventory replenishment will be important indicators of whether the current supply tightness is temporary or developing into a more persistent constraint.
At the same time, traders will be monitoring the strength of the AI investment cycle. Continued expansion of data centres and electricity infrastructure could provide a substantial source of long-term copper demand, although regulatory uncertainty in the United States remains a potential headwind.
The move towards $6.30 per pound represents a recovery from recent weakness, but sustained upward momentum will require evidence that physical supply constraints are translating into stronger buying activity.
Supply Outlook
The near-term supply picture is increasingly influenced by China, where reduced refined copper shipments and lower domestic smelter production are creating difficulties for inventory replenishment.
The diversion of copper towards the United States ahead of potential tariffs has further complicated international trade flows.
If Chinese smelter output remains constrained and import availability fails to improve, physical market tightness could continue supporting prices.
Demand Outlook
Demand expectations are being shaped by two competing forces.
On the positive side, AI infrastructure, data centre construction and electricity network investment remain important long-term drivers of copper consumption. Renewed investor confidence in the sector could strengthen expectations for future industrial demand.
On the negative side, uncertainty over US AI regulation could affect the speed of new infrastructure development. The extent to which this becomes a meaningful constraint on copper consumption will depend on actual policy decisions and their impact on investment.
China’s industrial demand and inventory replenishment will remain central to the short-term outlook.
Market Outlook for the Coming Sessions
Copper is recovering towards $6.30 per pound as tightening Chinese physical supply provides support following the recent decline to four-month lows.
Record import premiums, lower refined copper shipments and reduced smelter production have strengthened concerns over near-term availability. Renewed enthusiasm surrounding AI infrastructure has added further support by improving expectations for long-term industrial demand.
However, the market is not without risks. US political uncertainty and the possibility of tighter AI regulation could affect future data centre investment, while the sustainability of China’s supply constraints remains crucial.
For the coming sessions, traders will be watching Chinese import conditions, smelter output, inventory movements and developments in the global AI infrastructure sector. These factors will help determine whether the current rebound can develop into a more sustained recovery.
Currency Hedger – Contributor
Currency Hedger provides deliverable foreign exchange services, multi-currency accounts and currency risk management solutions for businesses operating internationally.
Open a Currency Hedger account | Visit Currency Hedger
Disclaimer: This market commentary is provided for informational purposes only and does not constitute investment advice, financial advice or a recommendation to buy or sell any financial instrument. Commodity markets involve substantial risk, and traders should conduct their own research and consider their financial circumstances before making trading decisions.

Leave A Comment