
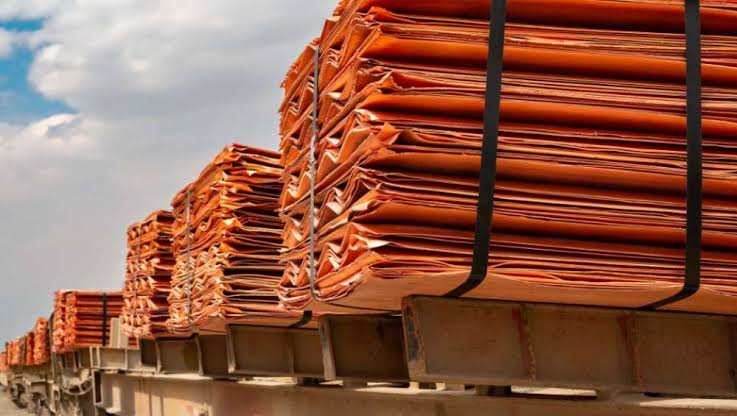
Copper futures are trading near $6.50 per pound, with prices under pressure as the market weighs conflicting signals from China against renewed concerns over global mine supply. China remains the dominant demand driver for industrial metals, and while improving manufacturing activity offers support, slower industrial-profit growth and reduced trading activity during the country’s extended holiday period are limiting near-term momentum.
At the same time, developments in Chile, Panama and the United States are keeping the supply outlook highly sensitive to political and operational developments. The copper market is therefore entering the next phase with a clear tension between improving Chinese manufacturing conditions and uncertainty surrounding mine production, refined-metal trade policy and global economic growth.
Market Snapshot
| Market Factor | Current Situation | What Traders Are Watching |
|---|---|---|
| Copper Price | Near $6.50/lb and around two-week lows | Whether support develops around current levels |
| China Manufacturing | Manufacturing activity returned to growth in September | Whether the improvement translates into stronger copper demand |
| Chinese Industrial Profits | Up 15.7% year-on-year in the first eight months | Evidence of further improvement or renewed slowing |
| Chile Supply | Potential disruption from strike action | Duration and impact on mine output |
| Panama Supply | Government has proposed restarting a major mine | Timing and scale of any production restart |
| U.S. Tariffs | Decision on refined copper tariffs remains delayed | Potential impact on trade flows and regional premiums |
| Near-Term Liquidity | Chinese holiday expected to reduce activity | Whether lower liquidity exaggerates price movements |
Current Copper Price Action
Copper remains vulnerable near $6.50 per pound, with futures recently reaching their lowest level in roughly two weeks.
The immediate pressure reflects a combination of softer momentum in Chinese industrial profitability, reduced market participation and uncertainty over the strength of physical copper demand.
However, the decline is not being driven by a uniformly weak fundamental picture. China’s manufacturing sector returning to growth provides an important counterweight, particularly because China accounts for a substantial share of global copper consumption.
The key question is whether improving manufacturing conditions can translate into stronger orders for copper-intensive sectors such as power infrastructure, construction, manufacturing and industrial equipment.
China Copper Demand Outlook
China remains the central demand variable for copper.
Industrial profits increased 15.7% during the first eight months of the year, but the pace slowed from the 17.6% increase recorded through the first seven months. That moderation suggests that the industrial recovery remains uneven.
More encouragingly, China’s manufacturing sector returned to growth in September. If this improvement persists, it could strengthen expectations for copper consumption and provide a foundation for a recovery in prices.
The market will therefore be watching whether the manufacturing improvement is sustained after the holiday period and whether it begins to generate stronger physical demand rather than simply improving sentiment.
Global Copper Supply Risks
Supply developments are becoming increasingly important as prices approach recent lows.
Potential strike action at a Chilean operation owned by Antofagasta introduces a fresh source of supply uncertainty. Any prolonged disruption could tighten concentrate availability and provide support to copper prices.
Panama represents the opposite supply story. The government’s proposal to restart operations at a major mine could eventually increase global production and ease some supply concerns if the restart progresses.
This creates an increasingly two-sided supply outlook: Chile introduces potential disruption risk while Panama could add future production.
Refined Copper and U.S. Tariff Uncertainty
U.S. trade policy remains another major variable for copper.
The Trump administration has so far delayed a decision on potential tariffs on refined copper. The uncertainty is important because any change in U.S. import policy could alter global trade flows, regional premiums and the availability of refined copper in different markets.
Until greater clarity emerges, traders may remain reluctant to establish aggressive directional positions based purely on tariff expectations.
Bullish Sentiment
- Chinese manufacturing has returned to growth, improving the outlook for industrial copper consumption.
- Potential Chilean strike action could restrict mine output and tighten the global concentrate market.
- Copper remains strategically important to power infrastructure, electrification and industrial investment.
- Any sustained improvement in Chinese industrial activity could quickly strengthen physical demand expectations.
- Trade-policy uncertainty could create regional supply distortions that support prices in affected markets.
Bearish Sentiment
- Copper has fallen toward two-week lows, indicating continued short-term selling pressure.
- Chinese industrial-profit growth has slowed, suggesting the manufacturing recovery remains uneven.
- The Chinese holiday period could reduce trading activity, limiting immediate demand signals and liquidity.
- A potential restart of major Panamanian mine operations could eventually increase global supply.
- Delayed U.S. tariff decisions are keeping manufacturers and traders uncertain about future refined-copper trade flows.
Price Forecast: What Traders Are Watching
Copper’s next major move is likely to depend on whether the market receives stronger confirmation of improving Chinese demand or increasingly significant evidence of supply disruption.
A sustained recovery in Chinese manufacturing combined with disruption at major mines could shift attention back toward tighter global balances and encourage buyers to return.
Conversely, if Chinese demand remains subdued while Panama moves toward restarting production and U.S. tariff uncertainty continues, copper could remain under pressure and retest lower technical support.
For now, $6.50 per pound is an important psychological area. The market’s ability to stabilize around this level will help determine whether the recent decline develops into a broader correction or becomes a temporary setback within a larger industrial-metals cycle.
Supply Outlook
The global supply picture remains mixed.
Potential disruption in Chile represents an immediate upside risk to prices, particularly if strike action affects meaningful production for an extended period.
Panama could provide additional supply over the longer term if its proposed mine restart progresses. The timing, scale and reliability of that production will be critical in determining how much additional metal reaches the international market.
The copper market therefore remains highly sensitive to operational developments at major mines.
Demand Outlook
Demand remains closely tied to China’s industrial cycle.
The return of manufacturing growth is constructive, but the slowdown in industrial-profit growth shows that the broader recovery is not yet uniform.
The next stage will depend on whether manufacturing expansion leads to stronger orders, inventory replenishment and infrastructure-related copper consumption.
Outside China, the market will also monitor global industrial activity and investment in electricity networks, renewable infrastructure and other copper-intensive industries.
Currency Hedger View
Copper remains particularly sensitive to movements in the U.S. dollar, as a stronger dollar can increase the effective cost of dollar-denominated commodities for international buyers.
For businesses purchasing copper or other industrial metals in international markets, currency movements can therefore amplify or offset changes in the underlying commodity price.
With copper caught between uncertain Chinese demand and changing global supply expectations, managing the FX component of international commodity exposure can become just as important as monitoring the copper market itself.
Coming Sessions
Traders will be watching:
- The sustainability of China’s manufacturing recovery.
- Further Chinese industrial-profit data and evidence of improving demand.
- Developments surrounding potential strike action in Chile.
- Progress toward a possible restart of mining operations in Panama.
- Any announcement regarding U.S. refined-copper tariffs.
- Copper’s ability to stabilize around the $6.50-per-pound area.
- Changes in the U.S. dollar that could influence international commodity demand.
Today Markets View
Copper is currently caught between improving Chinese manufacturing signals and persistent concerns over industrial demand. At the same time, supply-side risks in Chile and potential additional production from Panama are creating an increasingly balanced but highly event-sensitive outlook.
The next sustained move is likely to require confirmation from either side of the market. Stronger Chinese physical demand and mine disruptions would strengthen the case for a recovery, while continued demand weakness combined with improving supply availability could keep prices under pressure.
Analysis Louis Roche – Today Markets
Currency Hedger
For companies exposed to international copper purchases, sales or cross-border commodity payments, movements in the underlying copper price are only one part of the risk equation. Changes in the USD exchange rate can materially affect the final cost of international transactions.
Currency Hedger helps businesses manage international currency exposure through structured FX solutions, market analysis and access to global currency markets.
General market information and analysis provided by Octalas Group on behalf of Today Markets and Currency Hedger. This material is for informational purposes only and does not constitute investment advice or a recommendation to buy or sell any financial instrument.

Leave A Comment