
Today’s macroeconomic calendar is very light, while the scheduled quarterly earnings releases in the US are focused mainly on smaller companies, which may shift investors’ attention primarily toward Europe. In Europe, several large and market-relevant companies have already reported results today, including Siemens Energy, E.ON, RWE, ABN AMRO, Vestas Wind Systems and Swiss Life. Additional points of interest during the session include speeches from ECB officials and the OPEC Monthly Report. Economic calendar
- 7:00 AM GMT – Germany: Final HICP YoY: 2.8% (forecast: 2.8%, previous: 2.8%)
- 7:00 AM GMT – Germany: Final CPI YoY: 2.8% (forecast: 2.8%, previous: 2.8%)
- 7:00 AM GMT – Germany: Final HICP MoM: -0.1% (forecast: -0.1%, previous: -0.1%)
- 7:00 AM GMT – Germany: Final CPI MoM: -0.2% (forecast: -0.2%, previous: -0.2%)
- 9:00 AM GMT – Italy: Industrial Production MoM: forecast 0.7%, previous -1.3%
- 10:30 AM GMT – Germany: 30-year Bund yield: previous 3.8%
- 12:00 PM GMT – US: MBA Mortgage Applications: previous -1.2%
- 12:00 PM GMT – US: MBA 30-year Mortgage Rate: previous 7.30%
- 1:00 PM GMT – OPEC: Monthly Report
- 9:45 PM GMT – New Zealand: External migration and visitor arrivals; in September, the figure increased by 8% YoY
US corporate earnings
- Before the US market open: Rumble, Riskified, Sigma Lithium, Innoviz Technologies, ICL Group, CGI, EuroDry, Boyd Group Services, Aebi Schmidt, Oddity Tech, Valens Semiconductor, uCloudlink, Radcom, Polypid, Nayax, MiNK Therapeutics
- After the US market close: Osisko Gold Royalties, Franco-Nevada, Aevex, Okeanis Eco Tankers, EZCORP, Corteva, Integra Resources, Pelagos Insurance Capital, Teekay, Star Equity Holdings
- European corporate earnings: Siemens Energy, E.ON, RWE, ABN AMRO, Vestas Wind Systems, Poste Italiane, Swiss Life, Brenntag, voestalpine, Snam, Technoprobe, De’Longhi, Avio
Central bank speeches
- 7:50 AM GMT – Eurozone: ECB’s Cipollone speaks
- 8:10 AM GMT – Eurozone: ECB’s Kazaks speaks
- 8:20 AM GMT – Eurozone: ECB’s Nagel speaks
- 8:45 AM GMT – Eurozone: ECB President Christine Lagarde speaks
USDIDX chart (D1 interval)
The US Dollar Index futures contract is trading higher today, extending yesterday’s gains supported by a hotter-than-expected CPI reading and hawkish comments from Fed’s Waller, who signalled a potential need for a 50 bp rate hike in the US and indicated that, over time, some of the policy easing already delivered by the Fed could be reversed. Key resistance levels are located near 102.3 and 102.5, based on previous price reactions, while an important support zone can be found around 101.3, also reinforced by price-action methodology.
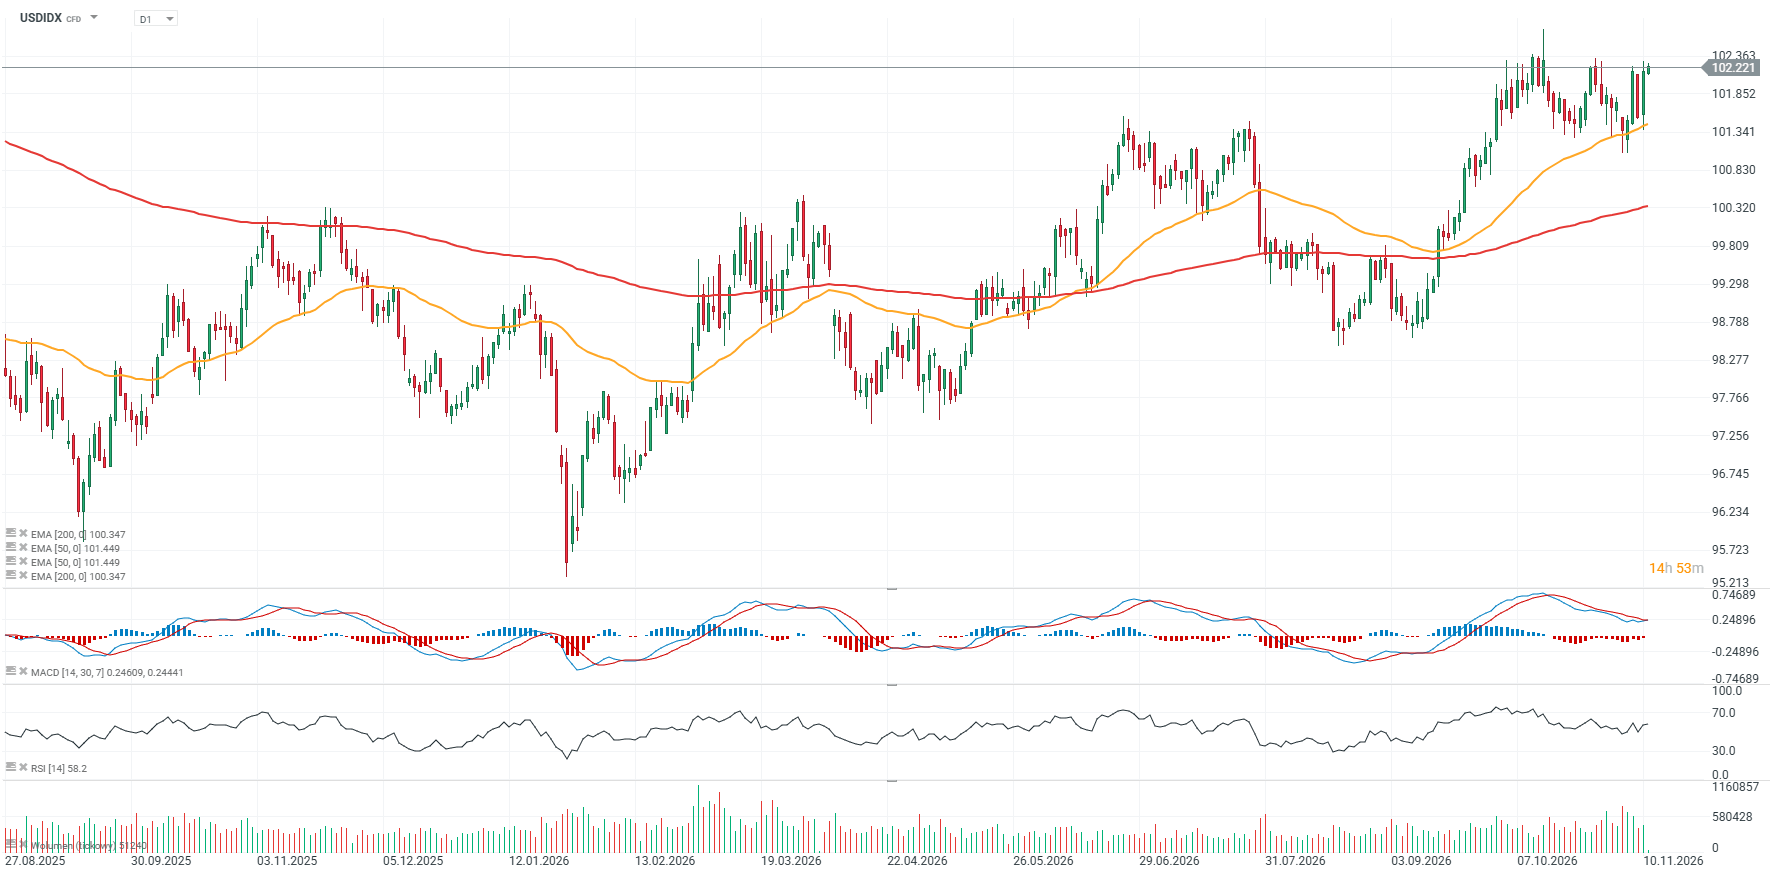
Source: xStation5

Leave A Comment